Buying a Home in Scotland: What You Need to Know Before You Move
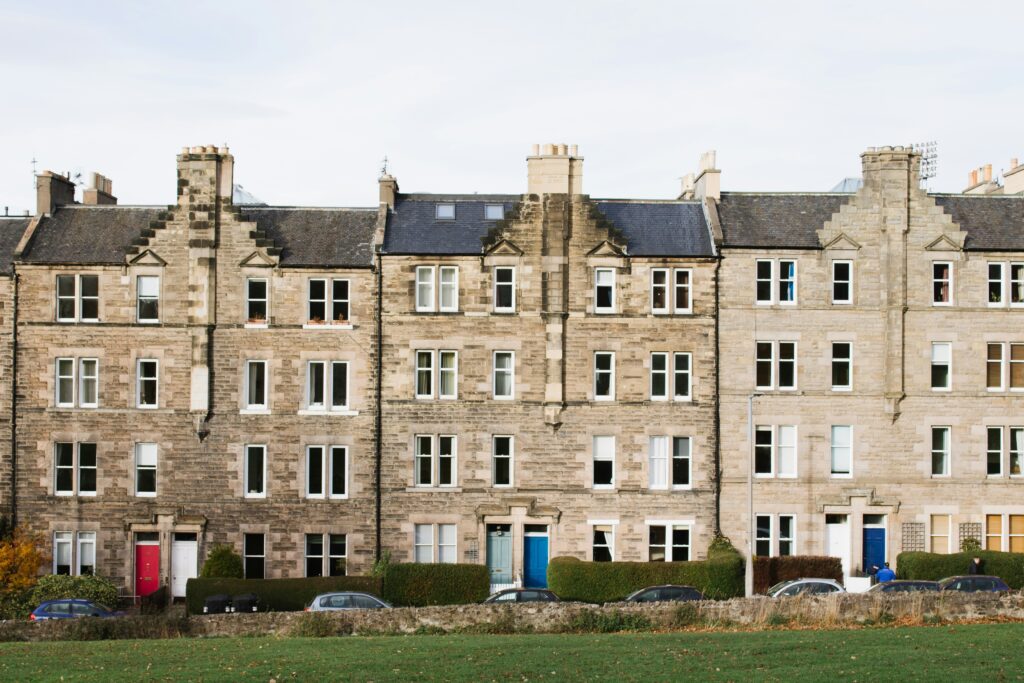
From Stamp Duty to property chains, there’s a lot to think about when buying a house and it’s important to balance heart and head when making such a big decision. In fact, over 99,000 residential properties were sold across Scotland in the 2024–25 financial year. To help ease the process, Legal & General breaks down the key things to consider and help make the process as smooth as possible.
Can You Afford to Move?
Buying a home is about more than just the mortgage. You’ll need to budget for several other costs, including:
- Mortgage fees – Arrangement and booking fees can range from £1,000 to £2,000.
- Legal fees – Solicitors or conveyancers typically charge £850 to £1,500.
- Estate agent fees – If you’re selling too, expect to pay 1%–3.5% + VAT of the sale price.
- Surveys – A HomeBuyer’s Report costs a few hundred pounds but can save money long term.
- Other costs – These include removals, storage, insurance, and potentially Stamp Duty (check the latest thresholds at GOV.UK).
How Stable Is Your Situation?
Before committing to a purchase, consider your long-term plans:
- How long will you stay? On average, Brits stay in the same home for around 23 years.
- Is your income stable? Mortgage lenders prefer applicants with steady, permanent employment.
- Are you tied to an area? If you’re committed to a location due to work, schools, or family, it’s worth choosing a home that will suit your needs for years to come.
How Much Can You Borrow?
Your borrowing power depends on your income, deposit size, and overall financial health. Generally:
- A 5% deposit is the minimum, but a bigger deposit gives you access to better mortgage deals.
- Most lenders offer up to 4.5 times your annual salary.
Using a mortgage adviser can help you find the right deal for your circumstances.
What to Look for in a Home
Once you know your budget, it’s time to think about what matters most in a property. Consider:
- School catchments – Sites like Locrating can help you research local schools.
- Commute – Factor in travel time, fuel costs, or train season tickets.
- Resale value – Look into any planned developments nearby or rising local demand.
- Maintenance needs – Would you prefer a renovation project or a move-in-ready home?
10 Smart Questions to Ask at a Viewing
It’s easy to fall in love with a property during a viewing – but don’t forget to ask the practical questions too:
- How long have the current owners lived here?
- Why are they selling?
- Have there been any offers?
- Have previous sales fallen through?
- Is the seller in a chain?
- How soon are they looking to move?
- What’s included in the sale (e.g. garden buildings or land)?
- When were major upgrades last done (roof, boiler, windows)?
- Are any major works planned in the area?
- Have there been any issues with neighbours?
How Long Does It Take to Buy a House?
Typically, the process takes 4–5 months from your first viewing to completion. First-time buyers may move quicker, especially when purchasing a chain-free property. But timelines can stretch if the seller hasn’t found their next home or you’re buying a probate property.
Should You Get Life Insurance When Buying a Home?
It’s not a legal requirement, but some mortgage lenders may insist on life insurance. Even when optional, many homeowners choose a policy – such as decreasing life insurance – that would cover their mortgage if they passed away during the term.
Buying a house is one of the biggest financial decisions you’ll ever make. While there’s no one-size-fits-all approach, understanding your options, preparing your finances, and asking the right questions can help you make confident and informed choices. For more information, visit here: https://www.legalandgeneral.com/insurance/life-insurance/guides/what-to-consider-when-buying-a-house/